The Roof Over Your Head: What Florida Homeowners Need to Know About Roof Age & Insurance
If you’ve bought or sold a home in Florida recently, you’ve probably heard one question over and over: “How old is the roof?”
In today’s Florida real estate market, the age and condition of a roof can have a significant impact on homeowners’ insurance, and that can affect both buyers and sellers. But there is a lot of confusion surrounding Florida’s roof-age rules. So, let’s separate fact from fiction.
Is a 15-Year-Old Roof Automatically Uninsurable? The answer is, No.
*Florida law does not say that a roof must be replaced when it reaches 15 years old. In fact, Florida law provides protections for homeowners with older roofs. If a roof is less than 15 years old, an insurance company generally cannot refuse to issue or renew a homeowners’ policy solely because of the roof’s age. For a roof that is 15 years old or older, the homeowner must be allowed to have the roof inspected by an authorized inspector before an insurer requires replacement based solely on age. And here’s the part many homeowners don’t realize:
If that inspection determines the roof has at least five years of useful life remaining, an insurer cannot refuse to issue or renew the homeowners’ policy solely because of the roof’s age.
So why are we hearing so much about 15-year-old roofs? Because age is only one piece of the insurance puzzle. Insurance companies may consider the condition of the roof, its remaining useful life, the construction and location of the home, wind resistance, mitigation features and other underwriting factors.
Florida law specifically provides that insurers may consider factors beyond age when determining whether to provide coverage. That means a 16-year-old roof isn’t necessarily a problem—and a 10-year-old roof isn’t automatically guaranteed coverage. Condition is what matters most!
What Happens When You’re Buying or Selling a Home?
This is where the issue becomes especially important in a real estate transaction.
For Buyers
Before you fall in love with a home, it’s smart to understand:
How old is the roof?
When was it last replaced?
Is there documentation showing the replacement date?
What type of roofing material was used?
Has the roof been repaired or partially replaced?
Does the roof have an inspection documenting its remaining useful life?
What insurance options are available for the property?
What will the premium and deductibles look like?
A buyer shouldn’t assume that an older roof automatically means “no insurance.” At the same time, buyers should never assume that Florida’s 15-year rule guarantees that an insurance company will offer a particular policy or price. Insurance underwriting is property-specific.
For Sellers
If you’re preparing to sell a home with an older roof, documentation can be extremely valuable.
Keep copies of:
The original roof permit, if available
The contractor’s invoice
Warranty information
Receipts for repairs
Previous roof inspections
Insurance inspection reports
Wind mitigation reports
Any documentation showing when the roof was repaired or replaced
Good documentation can make the insurance conversation much easier for the next homeowner.
Don’t Forget About the Roof Deductible
There’s another important part of Florida’s insurance rules that homeowners should understand.
Florida insurers may offer a separate roof deductible of up to 2% of the home’s Coverage A dwelling limit or 50% of the cost to replace the roof, whichever is less. For example, if a home has $500,000 in Coverage A, 2% would be $10,000. That’s potentially a very different financial consideration than simply asking, “How old is the roof?”
The policyholder must be offered the ability to decline this separate roof deductible, and the insurer must provide a premium credit or discount for selecting a policy with one. Certain types of losses, including hurricane damage, are excluded from application of the separate roof deductible under the statute.
What About Roof Inspections?
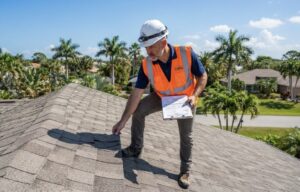
A roof inspection can be an important piece of the puzzle, particularly with an older roof.
Florida law allows an authorized inspector to evaluate the roof’s remaining useful life. The law identifies several categories of professionals who may qualify, including licensed home inspectors, building-code inspectors, certain contractors and roofing contractors, engineers and architects, provided they meet the applicable requirements and are approved by the insurer. We recommend Silvers Roofing. LIC # CCC1336463 Call Robert 1-239-315-8726 direct
And remember: the insurance company may have its own underwriting requirements and may require its own inspection or documentation. That’s why it’s wise to talk with an insurance professional early; NOT the day before closing!
The Bottom Line for Florida Homeowners:
The biggest takeaway is simple: Don’t automatically write off a home because it has a roof that is 15 years old—or assume that a newer roof guarantees insurance coverage. Florida’s insurance laws provide important protections concerning roof age, but insurance companies still evaluate the overall risk and condition of the property.
For buyers, understanding the roof and insurance situation before making an offer—or during the inspection and due-diligence period—can prevent unpleasant surprises later.
For sellers, having your roof records and insurance-related documentation organized before putting your home on the market can help make the transaction smoother.
As always, real estate professionals can help you understand the real estate side of the transaction, but your insurance agent is the right person to determine whether a particular property qualifies for coverage and what that coverage will cost.
In Florida, the roof over your head isn’t just part of the home’s exterior. It’s an important part of the home’s insurability, too. The NaplesRealEstate.com Team understands all the nuances of buying and selling homes. They know how to anticipate a potential issue before it becomes a problem. Their knowledge and guidance will make the entire transaction close as smoothly and as stress-free as possible.
If you are considering buying or selling a home in Southwest Florida, please call the NaplesRealEstate.com Team. They hope to hear from you soon, and they look forward to earning your future real estate business and trust! 1-239-404-4889
In Florida real estate it pays to look beyond the roof you see and understand the coverage that protects everything beneath it!
The Naples Real Estate Blogger
*One important clarification from the current 2026 Florida statutes: there is not a new blanket rule saying a Florida home must have a roof under 15 years old to be insured. The 15-year rule is actually a protection for homeowners. If a roof is less than 15 years old, an insurer cannot refuse or renew a homeowners’ policy solely because of the roof’s age. Once the roof is 15 years or older, the homeowner must be allowed to obtain an inspection before the insurer requires replacement, and if that inspection shows at least five years of remaining useful life, the insurer cannot refuse coverage solely because of the roof’s age. There are also important distinctions between Florida law and an individual insurance company’s underwriting requirements which is something we think is particularly valuable for our clients to understand. However, Florida law does not prevent an insurer from declining a property for other lawful underwriting reasons.